Tala Review: Is It Legit? Rates, Limits and Red Flags
Contents
- Tala at a glance: the facts we verified
- What is Tala?
- How to borrow from Tala: the official steps
- The real cost of a Tala loan: the honest gap
- Pros and cons
- What to know before you apply
- Red flags: fake Tala apps are the real danger
- Tala alternatives worth checking
- FAQ
- Verdict: who should (and should not) borrow from Tala
The Tala loan app promises up to ₱25,000, with a repayment date you pick yourself, up to 61 days out. The company behind it, Tala Financing Philippines Inc., holds Certificate of Authority 1132 from the Securities and Exchange Commission (SEC). That is the good part. The catch is pricing: Tala publishes no interest rate and no fee schedule, so this review prints "not published" wherever the numbers are missing, instead of inventing them. Registry status verified September 16, 2026.
Tala at a glance: the facts we verified
Every row below comes from my September 16, 2026 check of official sources: the SEC registry, the recorded platforms list, and tala.ph. Where Tala stays silent, the table says so.
| Item | What we verified | Source |
|---|---|---|
| Lender of record | Tala Financing Philippines Inc. (financing company) | SEC financing companies registry, September 16, 2026 |
| SEC status | Registered; Certificate of Authority No. 1132, primary source | SEC registry |
| Online platform record | Listed in the January 26, 2026 SEC list of recorded platforms | SEC list, reprinted February 6, 2026 |
| Maximum limit | "up to ₱25,000" as your limit grows | tala.ph |
| First loan amount | Not published | tala.ph |
| Term | "Choose your own repayment date up to 61 days" | tala.ph |
| Interest rate | Not published | tala.ph |
| Fees | Amounts not published; the site says "no hidden fees" | tala.ph |
| Approval speed | "Online Loan up to ₱25,000 in 5 Mins" (site headline); "Apply within minutes, receive an instant decision" | tala.ph |
| Payout channels | No list published; "cash out from disbursement channels nationwide" | tala.ph |
| Requirements | Age not published; one valid ID per a customer testimonial | tala.ph |
| Official site | tala.ph | tala.ph |
Two rows say "not published" on purpose. Most reviews fill that silence with estimates or borrowed numbers. We will not. A missing rate is a fact about Tala, and it matters more than any figure we could borrow.
What is Tala and who runs it?
Tala is the Philippine arm of a global consumer-lending brand run by InVentiv, operating locally through Tala Financing Philippines Inc. It is a financing company: registered with the SEC and holding a Certificate of Authority. Source grade matters here. Its CA, number 1132, comes from the SEC's own financing companies registry rather than from a company footer. That is the strongest one we use.
Positioning is the interesting part. Tala markets itself to borrowers other apps turn away: "ginawa para sa first-time borrowers, may irregular income, at walang traditional credit history." First-timers, irregular income, no credit file. The service runs through a mobile app, with tala.ph as the official website (tala.co/ph returns a 404; yes, I tried it). No branch network or web application path is published. The app is the only documented door in.
How to borrow from Tala: the official steps
Tala's process runs entirely inside the app: install, apply, submit one valid ID, pick a repayment date up to 61 days out, and cash out. Officially, that is most of what is documented. Here is every step I could confirm from the company's own pages, with the gaps marked.
- Install the app through an official channel. Start at tala.ph and follow its download link; our check could not verify a Philippine App Store listing.
- Register and apply. "Apply within minutes, receive an instant decision," the site says. A claim, not a guarantee.
- Submit what is asked. The only requirements evidence on record is a customer testimonial: "Isang valid ID lang ang hiningi nila." One valid ID. No document list and no minimum age are published.
- Pick your repayment date. Borrowers choose their own date, up to 61 days out.
- Cash out. Approved money goes through "disbursement channels nationwide," per the site. Which channels exactly, Tala does not say.
Notice what is missing from that list. No published interest rate, no fee table, no late-payment penalty. That absence is the heart of this review.
The real cost of a Tala loan: the honest gap
This is where the review turns uncomfortable. Six years of covering consumer credit taught me one rule: silence on price is never an accident. Tala publishes no numeric interest rate and no fee amounts on its official site. The single mention of interest anywhere in the company's material is a customer testimonial: "hindi rin mataas ang interest rates nila." A testimonial is not a rate. Our Tala interest rate page is the honest zero: everything Tala publishes, and the way to price your own offer.
Price secrecy kills comparison, and comparison is the whole point of shopping for a loan. Philippine law agrees. The Truth in Lending Act (RA 3765) requires creditors to put the finance charge in pesos and centavos, and the equivalent simple annual rate, in writing before the transaction closes. If the numbers appear only after you tap agree, that deserves a hard look.
Until Tala publishes its pricing, the burden shifts to you. Five checks. Run them on the offer screen before you confirm:
| Check | What to look for |
|---|---|
| Amount you receive | The exact pesos credited to you, after any deduction |
| Total repayment | Everything you will pay back: interest plus every fee |
| Fee names | Any processing, service, or disbursement charge, named and quantified |
| Due date | The exact date, matching the one you chose |
| Late penalty | What a missed payment adds; Tala publishes no figure today |
Once you have those numbers, the math takes one minute. Our loan calculator uses the effective-APR formula we apply to every app: everything you repay minus what you actually received, divided by what you received, times 365 over the loan days, times 100 percent. Run your own offer through it. We will publish Tala numbers the day Tala publishes them.
Do not borrow against this review's estimate, because there is no estimate. Any site quoting a Tala interest rate today is quoting something Tala itself does not publish. Treat that as a red flag, not a fact.
Pros and cons at a glance
The honest ledger, good and bad on the same scale.
Pros
- SEC registration in the strongest grade: CA 1132 from the SEC registry, plus a place in the January 26, 2026 recorded platforms list
- Limits that grow up to ₱25,000 as you build history with the app
- A repayment date you choose yourself, up to 61 days
- A public promise of fair treatment: "walang harassment, walang pananakot, at walang pag-contact sa personal contacts mo"
- Built for first-time borrowers, irregular income, no credit history
- A fast decision claimed: "Apply within minutes, receive an instant decision"
Cons
- No published interest rate, so you cannot price this loan against rivals before applying
- No published fee amounts, despite the "no hidden fees" slogan
- No published late-payment penalty
- Payout channels called "nationwide" without a single named channel
- App-only service, no web application, no published office route
- Starting limits can be tiny: one testimonial describes growth "from Php 200… sa Php 4,000"
- Minimum age and formal requirements not published
Six of those cons are the same con wearing different clothes: silence on price. Registration makes Tala legal. Transparency would make it comparable.
What to know before you apply
We looked for independent borrower reviews to balance the company's claims. We found none we could verify during this check. None at all. That honesty gap is why this section replaces the usual "what borrowers say" block.
The only borrower voices published anywhere in our corpus sit on tala.ph itself. One customer describes a limit that grew "from Php 200… sa Php 4,000." Another says "hindi rin mataas ang interest rates nila." A third was asked for "isang valid ID lang." Those are testimonials the lender chose to display. Marketing, not evidence.
Before you apply, work through this list:
- Read the offer screen before accepting: amount received, total repayment, every named fee.
- Screenshot the offer and the disclosure. If the app shows nothing, remember that it showed nothing.
- Confirm the due date matches the date you picked, up to 61 days out.
- Ask what happens if you pay late. No penalty figure is published today, so get the answer in writing inside the app.
- Check the disbursement channel first, so you know where the money lands.
Five minutes of reading beats a month of surprises.
Red flags: fake Tala apps are the real danger
The biggest threat to a Tala borrower in 2026 is not Tala. It is everything pretending to be Tala.
In June 2026 the SEC warned about three clones of the Tala brand: Tala-Cash Loan Philippines, Tala AISI-loan app quickly, and Tala Shuk Lending Inc. Impersonation and phishing were the stated grounds, per Business Inquirer (June 13, 2026). Two warnings in three months. The March advisory already listed fake Tala clones in app stores: Tala Peso, Tala CashPro, Tala Loan, TalaCash, and Tala Pera, plus an unregistered app called Napaka Tala.
How to tell the real one from the fakes:
- The real Tala operates through Tala Financing Philippines Inc. under CA 1132. A clone has nothing verifiable. Cross-check on our Tala SEC status page.
- Download only through the official channels linked from tala.ph.
- If a "Tala" offer asks for money before releasing your loan, stop. Upfront cash demands sit on our loan app red flags checklist.
- Run any doubtful name against the illegal loan apps list we keep wave by wave.
Tala alternatives worth checking
Three registered options if Tala's missing price is a deal-breaker. All statuses checked against the SEC registry on September 16, 2026.
MoneyCat. CA 1254, a registered financing company. Its site promises a first loan at 0 percent interest with no processing fee, and publishes its rate ceiling openly: 11.9 percent per month, up to 145 percent APR. Amounts run ₱500 to ₱20,000. One caveat: the Android app ships as a direct download, not through Google Play. Full breakdown: MoneyCat review.
Fast-approval picks. If speed is the whole game, our roundup of fast-approval loan apps ranks registered apps by how quickly the money actually lands. Every pick passes the same SEC gate we applied to Tala.
Mabilis Cash. CA 1327, a financing company converted from a lending license. Google Play lists limits of ₱2,000 to ₱90,000 and a maximum APR of 131 percent, with the full amount disbursed and no hidden charges claimed. Fair warning: clones faked Mabilis Cash too in the June 2026 wave. Details: Mabilis Cash review.
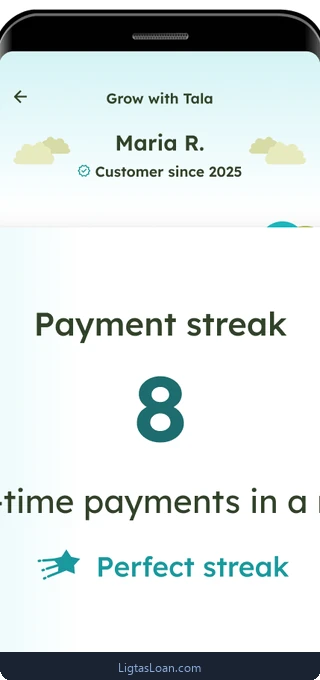
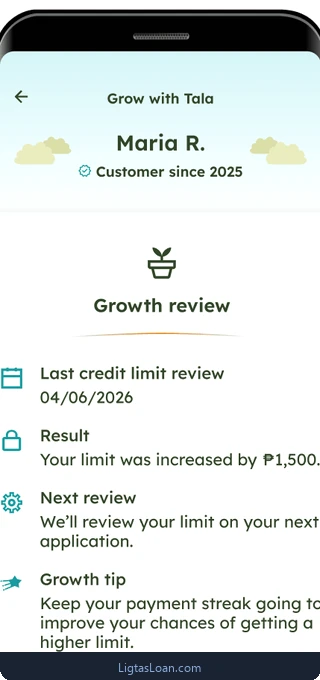
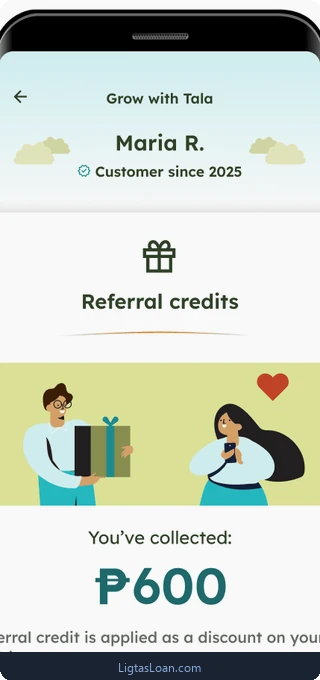
App screenshots of Tala
Real screens from the official tala.ph site, retrieved September 2, 2026, resized and watermarked for this site. Tala publishes no store listing we could open, so the lender's own site is the primary source.
Frequently asked questions
Is Tala SEC registered?
Yes. Tala Financing Philippines Inc. holds Certificate of Authority 1132 in the SEC financing companies registry, verified on September 16, 2026. Tala also appears in the SEC recorded online lending platforms list released January 26, 2026.
Is Tala legit ba or scam?
The lender itself is registered. Tala Financing Philippines Inc. holds CA 1132 and appears in the January 26, 2026 online lending platform list. Clones are the real scam risk. In March and June 2026 the SEC flagged fake apps posing as Tala, among them Tala Peso, Tala CashPro, and Tala-Cash Loan Philippines. Verify the entity before you borrow, and download only through official channels from tala.ph.
Does Tala call your contacts?
Tala publicly promises it does not. Its borrower-protection post on tala.ph says "walang harassment, walang pananakot, at walang pag-contact sa personal contacts mo": no harassment, no intimidation, no contacting your personal contacts. That is a company promise, not independently verified evidence. Screenshot it if you apply. Registered lenders also face fair-collection rules under MC 20, series of 2026, in force since August 1, 2026.
How much can I borrow in Tala?
Tala says limits grow up to ₱25,000 as you build history with the app. The starting amount is not published. One customer testimonial on tala.ph describes a limit that rose from Php 200 to Php 4,000, so expect to start small and grow.
Is Tala safe in the Philippines?
The registered lender is as safe as a licensed financing company gets: CA 1132, primary source, active in the 2026 platform list. The real danger is impersonation. Two SEC advisories in 2026 named fake Tala apps, so the safety rules are simple: install only via tala.ph, confirm the entity name before paying anything back, and check doubtful names against the SEC list.
Verdict: who should (and should not) borrow from Tala
So should you borrow from Tala? Scenario by scenario:
- First-time borrower, small emergency amount, no credit history. Tala is one of the few registered apps built for you. The missing rate still demands a slow read of the offer screen before you tap agree.
- Comparing cost across apps. You cannot, not yet: Tala publishes no rate to compare. Get the offer first, run it through our loan calculator, then decide.
- A big amount needed today. Limits grow with history, and the ceiling is ₱25,000. For larger first-time needs, a registered rival with published limits fits better.
- A "Tala" app asked you for an upfront fee. That is not the registered product. Check it against the fake-name list before you pay anything.
The verdict, then. Tala the company clears the bar: SEC registered, recorded platform, active status as of September 16, 2026. Tala the product keeps its price in the dark, and that costs you comparison power even though it is not a scam. Registration first, numbers second, signature last.